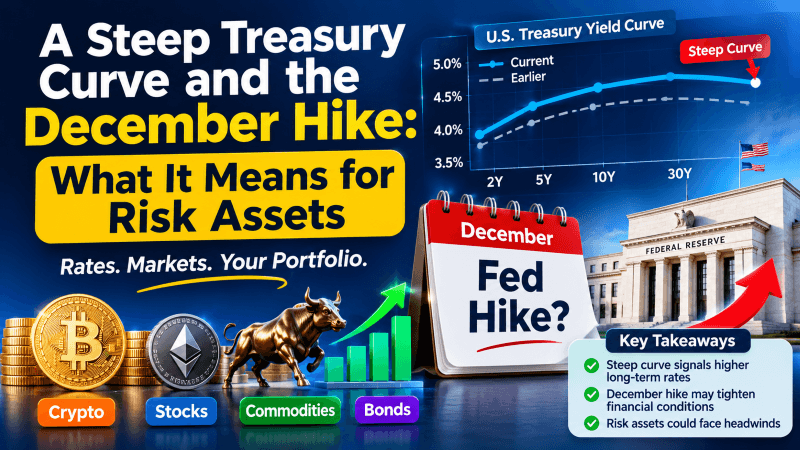
The U.S. Treasury curve ended the week of 2-6 Nov 2026 in a shape that is easy to read and hard to ignore. The 2Y yield held at 4.51% and the 10Y at 4.86%, while the 2Y-10Y slope stayed at +0.350% and the 10Y-30Y slope at +0.400%. That is a steep, fully dis-inverted curve. For crypto and other risk-asset readers, the message is that the front end is still shaped by a likely policy hike, while the long end is shaped by fiscal and corporate supply concerns.
The front end is pinned by a likely hike
The short end of the curve is not pricing a near-term easing path. The 2Y yield changed by -0.08% over the week, a small move that leaves it sticky at 4.51%. The report links that stickiness to non-farm payrolls rising 165,000 and inflation at 3.7% year over year. With Q3 GDP at 3.4%, the Fed under Chair Warsh is described as being in hiking mode, and December-hike odds are put at 70-80%, with one data point showing bets rising to 78% from 70%.
That matters because the 2Y is the tenor that most directly reflects near-term policy expectations. When the 2Y stays near 4.51% even as longer yields ease, it tells the market that the front end is not free to fall. The 3M yield at 4.19%, down -0.02% over the week, sits below the 2Y but still reflects a short-rate path that is anchored by the same policy outlook. It is being held up at the front by a Fed that is still expected to tighten.
The long end is carrying fiscal and AI supply risk
The long end moved in the opposite direction over the past month. The 10Y fell from 5.28% to 4.86%, and the 30Y fell from 5.67% to 5.26%. The 10Y also came down from an October 5.36% peak to around 4.83-4.90%, including a cited move of 13 basis points to 4.83%. That is a meaningful relief rally, but it did not flatten the curve. Instead, the 10Y-30Y slope remained at +0.400%, and the 2Y-10Y slope at +0.350%.
The reason is that the long end is not only responding to the Federal Reserve. It is also responding to fiscal mechanics and corporate debt supply. The report points to a >$40T national debt, a CBO deficit, and a structural fiscal backdrop that keeps a floor under long rates. It also highlights record corporate bond issuance by AI builders, with Magnificent Seven debt +45% to $578B. Cited estimates say the AI complex now owes $340-400 billion to the market and that AI debt to 2027 is 29% of new Treasury notes, bonds. Those are not small numbers. They suggest that the long end is absorbing more supply, not less, even when political headlines create a tactical relief rally.
The midterm result added a fiscal-restraint angle. Decisive Democratic control of Congress after the Nov 3 midterms shifted some bond-market thinking from fiscal expansion to fiscal restraint. That helped lift Treasuries and pull the 10Y down from its October peak. But the report is clear that the rally is capped. Political gridlock may constrain near-term spending, but it does not remove the underlying deficit or debt trajectory. The President still retains trade and foreign-policy powers, and structural long-end supply risk remains.
What the steep shape says for risk assets
For crypto and other risk assets, the takeaway is not that the curve is normal. The report describes it as a normal shape that is still aggressively steep. A normal curve can still be a warning sign when the steepness is driven by policy uncertainty, fiscal dominance, and corporate supply. The front end is trapped by an impending hike. The long end is trapped between gridlock relief and persistent structural deficits and corporate supply.
That combination argues against reading the recent long-end relief as a clean all-clear. The 10Y may have fallen from 5.28% to 4.86%, and the 30Y from 5.67% to 5.26%, but the curve is still steep. The 10Y-30Y spread at +0.400% suggests that investors are still demanding a large premium for holding longer-duration paper. The 2Y-10Y spread at +0.350% suggests that the market is not expecting the front end to fall quickly.
The week’s moves also show stabilization rather than a new downtrend. Yields retracted marginally across the board, with the 3M at 4.19% and -0.02%, the 2Y at 4.51% and -0.08%, the 10Y at 4.86% and -0.05%, and the 30Y at 5.26% and -0.02%. That is a pause after the early-October surge, not a confirmation that the long end has finished repricing.
For readers who follow crypto, the practical point is that the curve is a macro gauge of policy and fiscal stress. It shows that the short end is still being shaped by a likely December hike, while the long end is still being shaped by debt, deficits, and AI-related corporate issuance. That is a backdrop where risk assets may react to headlines, but the rate structure is not signaling a simple easing cycle. It is signaling a steep, bifurcated market: hawkish at the front, supply-heavy at the long end.
Author BIo
Pete writes for Weekly Market Reports, an independent macro research publisher; its weekly Yield Curve report is free at https://www.weeklymarketreport.com/yield-curve.
Disclaimer: This article is for educational and informational purposes only. It is not financial, investment, tax, or legal advice. Cryptocurrency is highly volatile, and investors can lose some or all of their capital. Always do independent research and consult a qualified professional before making investment decisions.