A trading channel can look convincing without proving much. A screenshot of a profitable chart, a list of winning tickers, or a claim of a high success rate may attract attention, but none of those details alone establishes that followers could have acted on the original idea or achieved the advertised result. A useful public record should make it possible to reconstruct what was known, when it was known, what would have invalidated the idea, and how the outcome was assessed.
This guide proposes a practical audit framework for educational crypto and stock trade ideas. The same questions can be used by a reader evaluating a public channel or by a publisher seeking to make its own work more accountable.
1. The original idea needs a timestamp
The first requirement is an original, accessible publication time. A record created after the price has already moved is not evidence of a timely forecast. The timestamp should be accompanied by the market symbol, trading venue or data source, and the price context available at publication.
A post such as ‘Bitcoin looks bullish’ is an opinion, not a complete trade plan. A stronger hypothetical example would specify that the idea concerns BTC/USD spot, identify the market-data source, state the condition that must occur before entry, and explain what would negate the thesis. The author should retain the original post rather than replace it after the outcome becomes clear.
Screenshots can help explain the idea, but a screenshot without a reliable publication history is weak evidence. When edits are necessary, a visible correction or follow-up is better than silently changing the initial claim. Readers should distinguish a public, pre-event record from a later reconstruction.
2. Separate an idea from an executed trade
An entry zone is not proof that an order filled. A price can touch a level briefly, gap through it, or trade there without sufficient available liquidity for a particular order. A credible journal therefore distinguishes at least four states: proposed, triggered, filled, and closed.
A proposed setup may never trigger. A triggered setup may not have been filled at the assumed price. A filled position can remain open, with an unrealized gain or loss. A closed trade has a realized outcome that still needs to account for execution and costs.
For a channel publishing analysis rather than actual personal trades, the journal should label the result as a hypothetical or model outcome. It should never describe a model fill as a verified personal fill. Where actual trades are claimed, independently verifiable brokerage or exchange records would be stronger evidence than an image alone, although privacy-sensitive account details should not be published.
3. Define the invalidation rule before the outcome
A setup should explain what observation would show that the original thesis is no longer supported. That might be a price level, a closing-price condition, a change in market structure, or a fundamental event. The rule should be precise enough that two careful readers could reach approximately the same conclusion.
For illustration only, imagine a hypothetical spot-market idea with an intended entry of $100, an invalidation level at $95, and an initial target of $110. The distance from entry to invalidation is $5, while the distance from entry to target is $10. The planned reward-to-risk ratio is therefore 2:1 before fees, slippage, and other costs. These numbers are not a live recommendation.
The arithmetic is simple; the harder question is whether the plan was published in advance and followed consistently. Moving the invalidation level after the price drops may turn a failed idea into an apparently ‘still active’ one. A transparent journal records that change as a new decision, with a new timestamp and rationale.
4. A stop is not a guaranteed exit price
It is tempting to calculate every stopped-out trade as though it exited exactly at the stated stop. That can understate losses. For securities, the U.S. Securities and Exchange Commission explains that a stop order becomes a market order when its trigger is reached, and the execution price may differ substantially from the stop price. A stop-limit order can control the minimum or maximum acceptable execution price, but it might not execute at all.
Crypto spot venues can also experience thin liquidity, spreads, abrupt price changes, exchange interruptions, and varying order rules. The applicable execution mechanics depend on the venue and instrument. Therefore a journal should distinguish the intended risk from realized loss and state its assumptions whenever a hypothetical stop outcome is calculated.
5. Show the full denominator, not only the winners
Suppose a publisher displays eight profitable trades. Eight out of what? If those are eight selected outcomes from 30 total ideas, the screenshot tells a very different story than eight wins from ten completed ideas.
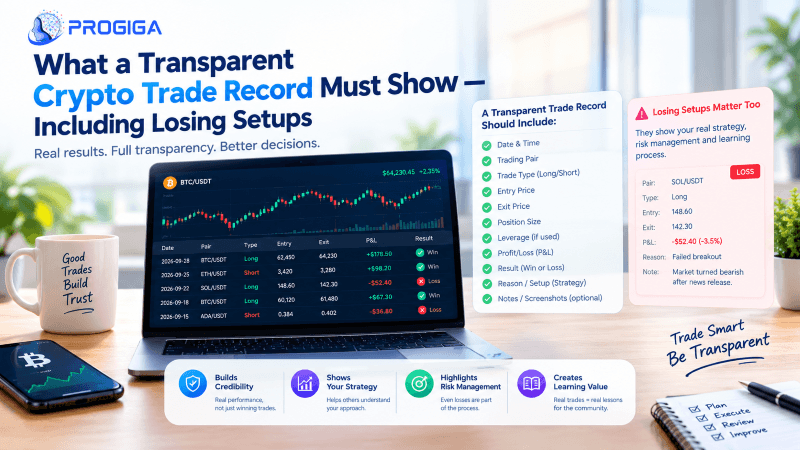
A meaningful record should include all published ideas over a defined period: winners, losers, open positions, cancelled ideas, setups that never triggered, and any ideas that cannot be evaluated because necessary data are missing. It should also say when the tracking period began. An honest new journal with a short history is more useful than an impressive-looking percentage whose denominator is hidden.
A win rate alone is not enough. For example, a strategy that wins 80% of the time but loses five units for each losing trade and earns one unit for each winner has a negative expected result before costs: 0.8 × 1 − 0.2 × 5 = −0.2 units per trade. A strategy with a lower win rate can have a different outcome if its gains and losses are structured differently. These are illustrative calculations, not performance estimates.
Readers should ask for the average gain, average loss, sample size, treatment of open trades, fees, and the maximum observed drawdown when relevant. If any of those figures cannot be verified, the journal should say so.
6. Define how outcomes are measured
Different publishers can use the same market move to report different ‘returns.’ One may calculate from the midpoint of a proposed entry range; another may use the most favorable intraday touch. One may assume the full target was reached; another may count a partial exit. Without a consistent methodology, performance figures cannot be compared fairly.
Before presenting a track record, a publisher should document its rules: which data source is used; whether entry requires a touch, a closing price, or a confirmed fill; how partial fills and exits are handled; whether stops and targets are checked against intraday high/low data; and how trading fees, spreads, and slippage are treated. If both a stop and target fall within the same historical candle, the outcome may be ambiguous without finer-grained data. It should not automatically be recorded as a win.
The CFA Institute’s Global Investment Performance Standards are designed for investment performance reporting and emphasize fair representation and full disclosure. A social-media trade journal is not the same as a GIPS-compliant investment performance presentation, and it should not claim compliance merely by following basic transparency practices. The broader principle remains useful: methodology and disclosure matter.
7. Preserve losing ideas and corrections
Losing setups are not embarrassing exceptions to be erased. They reveal whether a process is applied consistently and whether the author can explain mistakes without rewriting history. A useful postmortem states the original plan, what actually happened, whether the invalidation rule was reached, the assumed or actual exit, and what the outcome does or does not teach.
A cancelled idea deserves a record too. If a proposed entry never triggers, it should not be counted as a profitable trade simply because the market eventually moves in the expected direction. Similarly, a thesis that changes after a major news event should be identified as an updated view rather than retroactively attached to the earlier call.
Corrections are normal. The key is traceability. An erratum that identifies the affected post and explains the revision preserves more trust than deleting the original. Readers can then see both the initial uncertainty and the subsequent reasoning.
8. Watch for social-proof substitutes
Regulators have warned that investment scams can spread through social media and group chats. In a February 2026 alert, the SEC warned against making stock investment decisions based solely on social-media information and highlighted guaranteed returns and impersonation as red flags. The CFTC has also warned that trading signals, fabricated testimonials, and claims of effortless profits can be used to mislead people.
Those warnings do not mean every online educational channel is fraudulent. They do mean that audience size, testimonials, polished graphics, and confident language are not substitutes for verifiable records. A responsible reader should verify the source, assess conflicts of interest, and avoid relying on a single channel to make financial decisions.
9. A seven-question reader checklist
Before relying on any public trade record, ask:
- Was the original idea published before the relevant price movement?
- Is the asset, market, data source, and entry condition clearly identified?
- Was the invalidation rule documented before the result?
- Are model outcomes separated from verified executions?
- Are losing, cancelled, untriggered, and open ideas retained?
- Are returns calculated with a consistent method that explains costs and execution uncertainty?
- Are conflicts of interest, corrections, and limitations disclosed?
If several answers are missing, the right conclusion is not necessarily that the publisher is dishonest. It is that the available evidence is insufficient to evaluate the claim.
Conclusion
A transparent trade record does not promise profitability. It creates a trail that readers can examine, challenge, and learn from. The strongest journal is not the one with the most dramatic winning screenshot. It is the one whose original ideas, assumptions, invalidations, losses, and corrections remain visible when the market does not cooperate.
The purpose of a public journal should be to make reasoning auditable, not to turn uncertainty into marketing certainty. This article is educational and is not personalized investment advice.
References
U.S. Securities and Exchange Commission, ‘Stop, Stop-Limit, and Trailing Stop Orders’ (updated August 18, 2026): https://www.investor.gov/introduction-investing/general-resources/news-alerts/alerts-bulletins/investor-bulletins-15
U.S. Securities and Exchange Commission, ‘Social Media and Stock Tip Scams’ (February 6, 2026): https://www.investor.gov/introduction-investing/general-resources/news-alerts/alerts-bulletins/investor-bulletins/social-media-stock-scams
Commodity Futures Trading Commission, ‘There’s Nothing to Like About Scammers on Social Media’: https://www.cftc.gov/LearnAndProtect/AdvisoriesAndArticles/nothing_to_like_about_social_media_scammers.html
CFA Institute, background on the Global Investment Performance Standards: https://www.cfainstitute.org/about/press-room/2023/pif-announces-gips-compliance
Author bio
Yassine Abidallah publishes Nexalpha, a free Telegram channel covering educational, long-only crypto and stock setups with attention to entries, invalidation levels, and transparent follow-up. Nexalpha does not promote leverage or futures. Join Nexalpha free: https://t.me/NEXALPHAHQ
Affiliation disclosure
The author operates Nexalpha. The proposed channel link is included for editorial consideration and may be omitted at the publisher’s discretion. No compensation or paid placement is requested.
Disclaimer: This article is for educational purposes only and is not financial advice. Cryptocurrency carries risk of total loss. Always verify addresses, test transactions, and secure your seed phrase. Buy hardware wallets only from official manufacturers.